Finance
Ruth Bader Ginsburg optimistic ‘over the long haul’ for US
Quis autem vel eum iure reprehenderit qui in ea voluptate velit esse quam nihil molestiae consequatur, vel illum qui.

At vero eos et accusamus et iusto odio dignissimos ducimus qui blanditiis praesentium voluptatum deleniti atque corrupti quos dolores et quas molestias excepturi sint occaecati cupiditate non provident, similique sunt in culpa qui officia deserunt mollitia animi, id est laborum et dolorum fuga.
Quis autem vel eum iure reprehenderit qui in ea voluptate velit esse quam nihil molestiae consequatur, vel illum qui dolorem eum fugiat quo voluptas nulla pariatur.
Temporibus autem quibusdam et aut officiis debitis aut rerum necessitatibus saepe eveniet ut et voluptates repudiandae sint et molestiae non recusandae. Itaque earum rerum hic tenetur a sapiente delectus, ut aut reiciendis voluptatibus maiores alias consequatur aut perferendis doloribus asperiores repellat.
Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat.
“Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat”
Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt.
Et harum quidem rerum facilis est et expedita distinctio. Nam libero tempore, cum soluta nobis est eligendi optio cumque nihil impedit quo minus id quod maxime placeat facere possimus, omnis voluptas assumenda est, omnis dolor repellendus.
Nulla pariatur. Excepteur sint occaecat cupidatat non proident, sunt in culpa qui officia deserunt mollit anim id est laborum.
Sed ut perspiciatis unde omnis iste natus error sit voluptatem accusantium doloremque laudantium, totam rem aperiam, eaque ipsa quae ab illo inventore veritatis et quasi architecto beatae vitae dicta sunt explicabo.
Neque porro quisquam est, qui dolorem ipsum quia dolor sit amet, consectetur, adipisci velit, sed quia non numquam eius modi tempora incidunt ut labore et dolore magnam aliquam quaerat voluptatem. Ut enim ad minima veniam, quis nostrum exercitationem ullam corporis suscipit laboriosam, nisi ut aliquid ex ea commodi consequatur.
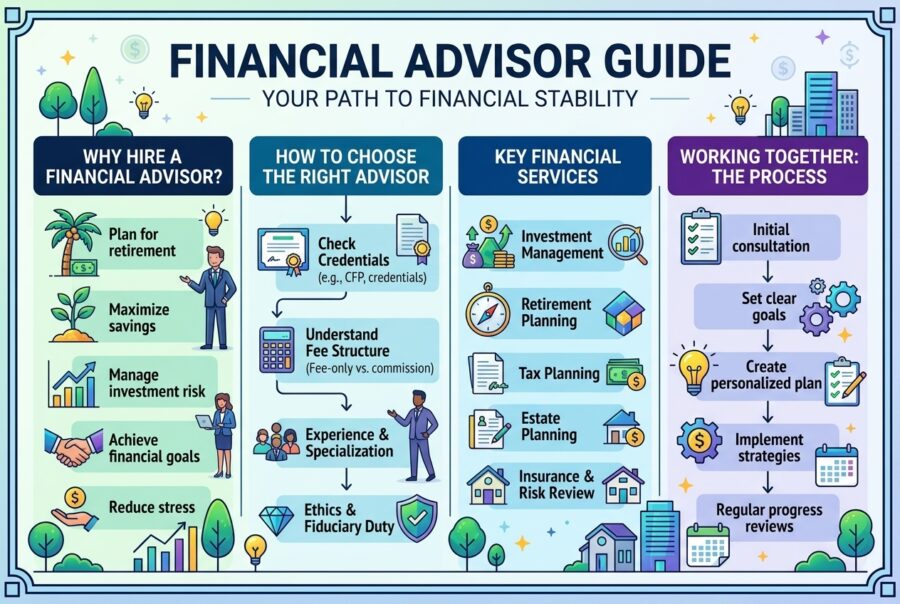
A financial advisor is a professional who helps people make decisions about money investments, retirement, taxes, insurance, estate planning, and overall financial goals.
The title is broad: some advisors are fiduciaries paid only by clients, others sell products for commissions, and many sit somewhere in between.
Choosing well matters because advice quality and incentives can change outcomes more than any single fund pick. The right advisor reduces costly mistakes. The wrong one adds fees, complexity, or conflicts you did not intend to buy.
Key Takeaways:
- “Financial advisor” is a broad label — inspect duty and pay model
- Fiduciary + fee-only is the cleaner structure for many ongoing relationships
- Fee-based is not the same as fee-only
- Robo-advisors are strong for simple investing, weaker for complex planning
- Convert percentage fees into real annual dollars
- Interview more than one advisor and demand written clarity
- Match the engagement type to the complexity of your life
Background: Why People Hire Financial Advisors?
Money decisions compound. A good plan coordinates:
- Cash reserves and debt
- Investment allocation
- Retirement contributions and withdrawal strategy
- Tax location and timing
- Insurance gaps
- Estate and beneficiary design
- Behavioral discipline during market stress
People hire advisors when the stakes feel high, the options feel overwhelming, or life events (marriage, divorce, inheritance, business sale, retirement) create complexity. Others hire for accountability — a structured process that keeps saving and rebalancing from slipping.
The industry evolved from product distribution toward planning and portfolio management, but both models still exist. That is why consumers must look past job titles and inspect standard of care and compensation.
Fiduciary vs Suitability: The Most Important Distinction
Fiduciary standard
A fiduciary must act in your best interest, put your interests ahead of their own, and generally avoid or disclose conflicts with a duty of loyalty and care. Registered investment advisers (RIAs) are commonly held to fiduciary duties under U.S. advisory law frameworks.
Suitability standard
A suitability obligation (historically associated with many brokerage recommendations) requires that a product fit your situation, but not necessarily that it is the best available option after conflicts are considered.
Practical takeaway: ask every candidate, in writing if possible:
“Do you act as a fiduciary at all times when advising me?”
Then verify how they are paid.
How Financial Advisors Get Paid?
Compensation drives behavior. Learn the vocabulary:
Fee-only
Paid solely by clients through:
- Assets under management (AUM) percentage
- Flat annual/retainer fee
- Hourly fee
- Project / one-time plan fee
No commissions from product sales. Often associated with fewer product-driven conflicts.
Fee-based
Charges client fees and may still earn commissions on some products. The name sounds similar to fee-only but is not the same.
Commission-based
Earns compensation primarily when you buy (or sometimes sell) products such as certain funds, insurance, or annuities.
Rule of thumb:
For ongoing comprehensive advice, many consumers prefer fee-only fiduciaries. For a one-time product need, commission channels may still appear — but you should understand incentives clearly.
What a Good Financial Advisor Actually Does?
Strong advisory relationships usually include:
- Discovery — goals, constraints, values, risk capacity
- Analysis — cash flow, net worth, gap analysis
- Written plan — prioritized actions, not generic slogans
- Implementation — portfolio, accounts, beneficiaries, savings rates
- Monitoring — rebalancing, tax opportunities, plan updates
- Coaching — decision support during volatility and life changes
Investment management is only one module. Planning coordination is often where human advisors outperform pure automation.
Credentials and What They Signal
Common credentials (verify current status):
- CFP® (Certified Financial Planner) — broad planning competency standard widely recognized for personal financial planning
- CFA® — investment analysis depth, often more portfolio/research oriented
- CPA / PFS — tax and planning strength
- ChFC, CLU — insurance/planning-related designations in some practices
Credentials are not guarantees. They are filters. Always combine credential checks with compensation review, fiduciary status, and complaint history searches through regulators where available.
Robo-Advisors vs Human Financial Advisors
Robo-advisors automate portfolio construction, rebalancing, and sometimes tax-loss harvesting for relatively low percentages of assets (often in the ballpark of roughly 0.15%–0.35% advisory fees before fund costs, depending on provider).
Human advisors cost more (AUM fees frequently measured in fractions of a percent to around 1%+, or flat retainers/hourly project fees) and can add planning breadth, tax coordination, estate integration, and behavioral coaching.
| Need | Often better fit |
|---|---|
| Simple long-term investing | Robo or low-cost DIY index portfolio |
| One-time comprehensive plan | Advice-only / hourly planner |
| Ongoing complex household planning | Human fiduciary advisor |
| Business sale, equity comp, multi-property taxes | Specialized human team |
| Accountability + custom withdrawal strategy | Human advisor |
| Lowest pure portfolio fee | DIY or low-cost robo |
Many households use a hybrid: automate investments, hire human help for high-stakes planning moments.
How Much Does a Financial Advisor Cost?
Illustrative ranges commonly discussed in consumer guides (always request a written quote):
- AUM model: often roughly 0.50%–1.00%+ per year depending on firm and asset level
- Hourly: often a few hundred dollars per hour
- One-time plan: commonly thousands of dollars depending on complexity
- Flat annual retainer: fixed yearly fee for defined services
- Robo advisory fee: typically lower percentage, limited planning scope
Convert percentages to dollars. On $500,000, 1% is $5,000 per year before underlying fund expenses. Ask what deliverables you receive for that cost.
Practical Tips: How to Choose a Financial Advisor?
- Define the problem — investments only, full plan, retirement income, tax coordination?
- Decide fiduciary expectation — prefer “yes, at all times.”
- Map compensation — fee-only, fee-based, or commission.
- Interview at least two candidates.
- Ask for a sample plan or meeting agenda.
- Request Form ADV / disclosures (or local equivalent) and read conflicts.
- Check credentials and disciplinary history.
- Clarify service model — who you meet, how often, what is out of scope.
- Get fees in writing, including fund expenses and third-party costs.
- Start with a defined engagement before moving large accounts, when possible.
Interview questions that surface truth
- Are you a fiduciary at all times?
- How are you paid, from every source?
- What conflicts do you have?
- What does the first-year process look like?
- What is not included in your fee?
- How do you handle taxes and estate coordination?
- Who performs portfolio trading and rebalancing?
Common Mistakes When Hiring an Advisor
- Mistake: Choosing based only on personality
Solution: Chemistry matters, but structure and incentives matter more. - Mistake: Confusing “fee-based” with “fee-only”
Solution: Ask whether any third-party commissions are possible. - Mistake: Paying AUM fees for a problem a one-time plan could solve
Solution: Match engagement type to complexity. - Mistake: Ignoring all-in costs
Solution: Add advisory fee + fund expenses + product costs. - Mistake: Handing over decision rights without understanding the strategy
Solution: Require plain-language IPS (investment policy) explanations. - Mistake: Never revisiting the relationship
Solution: Annual value review — progress vs fees vs responsiveness. - Pros and Cons of Working With a Financial Advisor
Pros
- Integrated planning across goals
- Professional portfolio process
- Behavioral guardrails in volatile markets
- Specialized help for taxes, equity compensation, retirement income
- Time savings and organized implementation
Cons
- Cost can be material over decades
- Quality varies widely
- Conflicts can exist depending on pay model
- Over-reliance may weaken personal financial literacy
- Bad advice is worse than no advice
Balanced verdict
A financial advisor is a tool. Hire one when complexity, stakes, or behavior gaps exceed what low-cost automation and self-education can handle. Skip or minimize ongoing fees when your needs are simple and your discipline is strong.
Also Visit: Financial statements
Future Trends in Financial Advice
- More transparent fee conversations driven by consumer awareness
- Growth of advice-only and flat-fee planning for people who do not need full AUM management
- Robo + human hybrids as default mass-affluent offers
- Tax and Social Security/retirement-income specialization as populations age
- AI-assisted analysis paired with human judgment on goals and tradeoffs
- Higher expectations for fiduciary clarity in marketing language
The winners will explain incentives simply and deliver measurable planning outcomes — not product volume.
Advice Models Compared
| Model | How paid | Typical strength | Main watchout |
|---|---|---|---|
| Fee-only fiduciary RIA | Client fees only | Conflict minimization, planning | Still compare dollar cost vs value |
| Fee-based advisor | Fees + possible commissions | Flexible product access | Dual incentives |
| Commission broker/agent | Product commissions | Transactional product help | Suitability vs best-interest tension |
| Robo-advisor | Low platform fee | Cheap automated investing | Limited complex planning |
| Hybrid robo + CFP access | Platform fee / tier pricing | Digital efficiency + some human help | Scope may be narrower than independent planning |
| Advice-only planner | Hourly/project/retainer | Planning without asset custody pressure | You implement yourself |
| Bank wealth desk | Mixed models | Convenience | Product shelf / referral dynamics |
| Insurance-focused agent | Commissions common | Risk-product expertise | May over-index on insurance solutions |
| Employer-provided advice | Employer-subsidized | Low friction | Limited household customization |
| DIY + education | Fund costs only | Lowest explicit fee | Behavior and knowledge burden |
Who Needs Which Type of Help?
| Situation | Practical fit | Why |
|---|---|---|
| Starting investor, simple goals | Robo or DIY index funds | Cost efficiency |
| First comprehensive plan | Hourly / project planner | Clarity without long lock-in |
| Dual-career household, growing assets | Fee-only fiduciary | Coordination value rises |
| Near retirement | Planner strong in income/tax sequencing | Sequence-of-returns and withdrawal risk |
| Equity compensation (RSUs/options) | Specialist human advisor + tax pro | Complexity beyond robos |
| Business exit / inheritance | High-capacity advisory team | Multi-entity, tax, estate issues |
| Insurance-only question | Transparent product specialist | Keep planning separate if needed |
| Anxiety-driven investing mistakes | Human coach-style advisor | Behavior is the product |
| Already disciplined DIY | Periodic advice-only checkup | Avoid unnecessary AUM drag |
| Very high net worth | Multi-specialist firm | Integration across legal/tax/investment |
FAQs
What does a financial advisor do?
Helps with financial planning and/or investments — goals, portfolios, retirement, taxes, risk coverage, and related decisions.
What is a fiduciary financial advisor?
Someone obligated to put your interests first when acting in an advisory capacity; confirm whether that duty applies at all times.
Is fee-only the same as fiduciary?
No. Fee-only describes pay. Fiduciary describes legal duty. They often appear together but are not identical terms.
How much does a financial advisor cost?
Models vary: AUM percentages, hourly rates, flat retainers, or project fees. Convert everything to annual dollars.
Do I need a CFP?
A CFP® is a strong planning signal for many households, but still verify fiduciary stance, fees, and fit.
Are robo-advisors worth it?
Often yes for straightforward automated investing; less complete for complex tax, estate, or retirement-income planning.
Can advisors guarantee returns?
No reputable advisor can guarantee market returns. Be wary of promises that sound certain.
How do I check an advisor’s background?
Use regulator databases and disclosure documents applicable in your country (for example, Form ADV-related disclosures in the U.S.), plus credential verification.
Conclusion
A financial advisor can be a powerful partner when incentives are clean, the scope matches your needs, and the advice is comprehensive rather than product-led. Start with fiduciary clarity, decode compensation, compare alternatives including robos and advice-only planning, and measure value in decisions improved — not glossy performance charts alone.
Quick Summary
A financial advisor helps with planning and investments, but quality depends on fiduciary duty, compensation, and scope. Prefer clear incentives, compare human vs robo options honestly, and hire for complexity you cannot efficiently manage alone.
Short Content Disclaimer
This article is general education, not personalized financial, tax, or investment advice. Regulations, titles, and fee norms vary by country and change over time. Verify credentials, disclosures, and contracts directly before engaging any advisor.
Authority sources:
Compensation definitions and fiduciary framing in this guide synthesize widely published consumer-finance explanations of fee-only, fee-based, and commission models, along with commonly reported robo-advisor versus human-advisor cost ranges. Always confirm current terms with the advisor’s official disclosures.
Source: WSJ
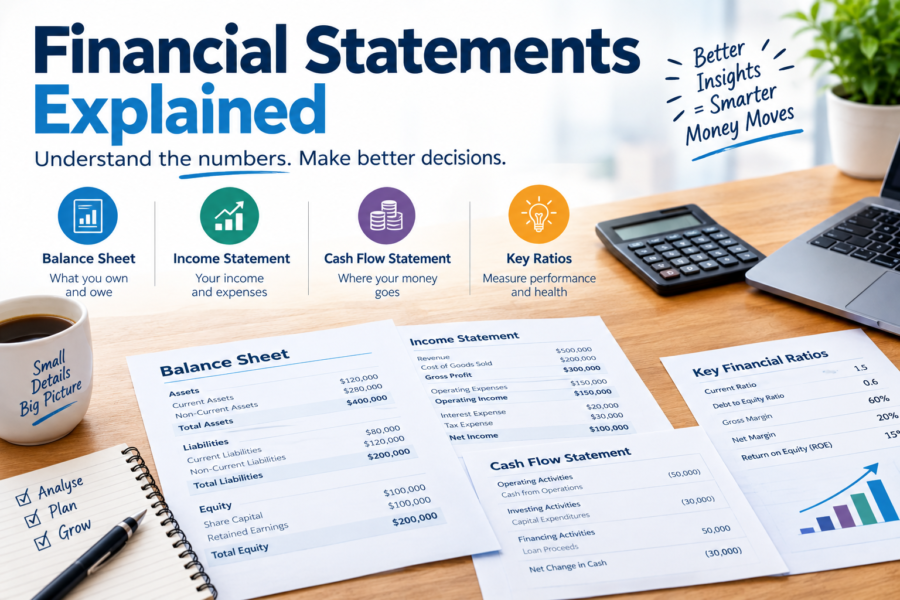
Financial statements are the formal reports that show a company’s financial performance and position — primarily the income statement, balance sheet, and statement of cash flows.
Together, they answer three practical questions: Did the business make an accounting profit? What does it own and owe? Where did the cash actually go?
Whether you are an investor, founder, student, or manager, learning to read financial statements is one of the highest-leverage skills in business. Numbers without context mislead. Context without numbers is guesswork. Financial statements sit in the middle.
Key Takeaways:
- The core trio is income statement, balance sheet, and cash flow statement
- Profit is not the same as cash
- The balance sheet must balance: assets = liabilities + equity
- Statement linkages are as important as individual totals
- Notes and policies are part of the analysis, not optional extras
- Ratios help, but only with context and comparability
- Framework differences (GAAP vs IFRS) affect cross-border reading
Background: Why Financial Statements Exist?
Businesses create value over time, but stakeholders need standardized snapshots. Owners, lenders, employees, regulators, and investors cannot all inspect every transaction. Financial statements translate thousands of journal entries into a shared language.
That language is shaped by accounting frameworks such as:
- U.S. GAAP (Generally Accepted Accounting Principles)
- IFRS (International Financial Reporting Standards)
Both aim for comparability and reliability, though rules differ on some classifications and measurement choices. Public companies publish statements regularly; private firms produce them for lenders, boards, and tax/management needs.
At the core is accrual accounting: revenues and expenses are recognized when earned or incurred, not only when cash moves. That is why profit and cash can diverge — and why you need more than one statement.
The Three Core Financial Statements
1) Income Statement (Profit & Loss)
Question it answers: How profitable was the business over a period?
Typical flow:
- Revenue (sales)
- − Cost of goods sold (COGS)
- = Gross profit
- − Operating expenses (SG&A, R&D, etc.)
- = Operating income
- ± Interest and other non-operating items
- − Taxes
- = Net income
Key traits
- Covers a period (month, quarter, year)
- Uses accruals and matching principles
- Best for margin trends and growth analysis
What smart readers look for
- Revenue quality (one-time spikes vs recurring growth)
- Gross margin direction
- Operating leverage
- Net income vs “adjusted” metrics management prefers
2) Balance Sheet (Statement of Financial Position)
Question it answers: What is the financial position on a specific date?
Fundamental equation:
Assets = Liabilities + Equity
Assets (what the company controls): cash, receivables, inventory, property, intangibles
Liabilities (what it owes): payables, debt, deferred revenue, accrued expenses
Equity (residual claim): capital contributed, retained earnings, other equity items
Key traits
- Point-in-time snapshot
- Must balance
- Links to cumulative profitability through retained earnings
What smart readers look for
- Liquidity (can near-term obligations be met?)
- Leverage (how much debt supports assets?)
- Working capital trends
- Asset intensity of the business model
3) Statement of Cash Flows
Question it answers: How did cash change over the period?
Three sections:
- Operating activities — cash from core business
- Investing activities — capex, acquisitions, asset sales
- Financing activities — debt, equity, dividends, buybacks
Most companies present operating cash flow using the indirect method, starting from net income and adjusting for non-cash items and working-capital changes.
Why it matters A company can show profit while burning cash (heavy receivables growth, inventory build, unpaid expenses timing). The cash flow statement reveals that tension.
How the Statements Connect
The statements are not isolated.
- Net income flows into retained earnings on the balance sheet.
- Net income is the usual starting point for operating cash flow.
- Ending cash on the cash flow statement should reconcile to cash on the balance sheet.
- Capex and financing decisions alter assets, debt, and equity simultaneously.
A practical reading order for beginners:
- Income statement for performance
- Cash flow statement for cash reality
- Balance sheet for resilience and obligations
- Notes for the assumptions behind the numbers
Notes, Equity Statements, and Comprehensive Income
Complete reporting packages often include:
- Statement of changes in equity
- Statement of comprehensive income (for certain gains/losses bypassing net income)
- Notes to the financial statements (accounting policies, debt terms, contingencies, segment data)
Professionals often spend as much time in the notes as on the face statements. Policies for revenue recognition, leases, impairments, and estimates can change the economic story materially.
Ratios That Make Statements Usable
Raw numbers become insight through relationships.
Profitability
- Gross margin = Gross profit / Revenue
- Operating margin = Operating income / Revenue
- Net margin = Net income / Revenue
- Return on equity (ROE) = Net income / Equity
Liquidity
- Current ratio = Current assets / Current liabilities
- Quick ratio = (Cash + receivables + marketable securities) / Current liabilities
Leverage
- Debt-to-equity
- Interest coverage = Operating income / Interest expense
Efficiency
- Inventory turnover
- Receivables days
- Asset turnover
Cash quality
- Operating cash flow vs net income
- Free cash flow approximations (operating cash flow − capex, with care)
Ratios are only as good as consistent accounting and comparable peer sets.
IFRS vs GAAP: Practical Differences Readers Notice
Framework differences show up especially in cash-flow classification and some measurement rules. Under common summaries:
- U.S. GAAP is stricter about classifying interest and dividends in operating/financing categories.
- IFRS allows more flexibility for interest and dividends classification in certain cases.
- Presentation and lease/impairment details can differ by standard and policy choice.
For global analysis, always check the basis of presentation note before comparing two companies from different regimes.
Practical Tips: How to Read Financial Statements Efficiently?
- Start with the business model — software, retailer, bank, and manufacturer do not “look” the same.
- Read multi-period comparisons — trend beats single-year snapshots.
- Reconcile profit to cash every time.
- Scan notes for revenue recognition and debt covenants.
- Separate operating performance from financing structure.
- Watch working capital in growing firms; growth can consume cash.
- Treat non-GAAP metrics as supplements, not replacements.
- Compare against peers and history, not absolute ideals.
- Follow cash returns to owners (dividends/buybacks) against leverage.
- Update your view when accounting policies change.
Common Mistakes and How to Avoid Them?
- Mistake: Equating net income with cash available
Solution: Use the cash flow statement before judging dividend capacity or runway. - Mistake: Ignoring off-face risks in notes
Solution: Read contingencies, related-party transactions, and commitments. - Mistake: Over-focusing on one ratio
Solution: Build a small dashboard across profitability, liquidity, and leverage. - Mistake: Comparing companies with different year-ends or standards blindly
Solution: Adjust for framework and seasonality. - Mistake: Trusting “adjusted EBITDA” without reconciling back
Solution: Map every adjustment to the audited statements. - Mistake: Forgetting that balance sheets are historical cost hybrids
Solution: Remember many assets are not current market values. - Mistake: Reading growth without capital intensity
Solution: Pair revenue growth with capex and working-capital needs. - Pros, Cons, and Limits of Financial Statements
Pros
- Standardized communication across stakeholders
- Historical accountability for management
- Foundation for valuation, credit analysis, and governance
- Comparable time series when policies are consistent
Cons / limitations
- Backward-looking by nature
- Estimates and judgments affect earnings
- Different standards reduce perfect global comparability
- Can omit important non-financial value drivers (brand strength, culture, pipeline quality)
- Vulnerable to aggressive accounting choices within rules
Balanced verdict
Financial statements are necessary but not sufficient. They are the best common starting point for economic reality — then you add industry knowledge, management quality, and forward indicators.
Future Trends in Financial Reporting
- More digital, machine-readable filings for faster analysis
- Greater attention to cash flow quality after cycles where profit outpaced cash
- Expanded sustainability and non-financial disclosures alongside traditional statements
- Continued IFRS/GAAP convergence pressures, with persistent local differences
- AI-assisted statement analysis that still requires human judgment on incentives and footnotes
- Segment transparency demands as conglomerates and platform firms grow more complex
The face statements will remain. The supporting data layer around them will thicken.
Tools and Sources Compared
| Resource / tool type | Best use | Strength | Limitation |
|---|---|---|---|
| Company annual report (10-K / IFRS annual) | Full statements + notes | Primary source | Dense for beginners |
| Quarterly reports | Timelier updates | Faster signal | Less complete than annual notes |
| Investor presentations | Management narrative | Strategy context | Selective emphasis |
| Excel / Google Sheets models | Custom ratio analysis | Flexible | Error risk if unchecked |
| Accounting textbooks / CFI-style explainers | Learning mechanics | Clear frameworks | Not company-specific |
| Bloomberg / FactSet / similar terminals | Professional comparables | Speed + depth | Costly |
| Free finance portals | Quick ratios and charts | Accessibility | May oversimplify notes |
| Auditor’s opinion section | Assurance signal | Independent check | Does not guarantee future performance |
| Segment note disclosures | Business-line insight | Mix clarity | Allocation judgments |
| Credit rating rationales | Debt-focused interpretation | Risk lens | Not equity valuation |
How Different Users Should Read Statements?
| User | Primary focus | Practical approach |
|---|---|---|
| Beginner investor | Profit trend + cash + debt | Simple margins, cash flow sign, leverage |
| Advanced analyst | Earnings quality + FCF drivers | Working capital, notes, peer bridges |
| Founder / operator | Runway and unit economics | Cash burn, gross margin, opex discipline |
| Lender / credit analyst | Coverage and collateral | Liquidity, covenants, maturity schedule |
| Job candidate / employee | Stability and trajectory | Revenue durability, cash generation |
| Student | Statement linkages | Build a three-statement model |
| Board director | Governance red flags | Policy changes, related parties, controls |
| Competitor strategist | Cost structure signals | Margin structure and reinvestment rate |
| Journalist | What changed and why | YoY bridges + footnote catalysts |
| Small business owner | Bookkeeping feedback loop | Monthly P&L + cash reality checks |
FAQs
What are the main financial statements?
The income statement, balance sheet, and statement of cash flows — often supplemented by equity statements and extensive notes.
What is the difference between an income statement and a balance sheet?
The income statement covers performance over a period; the balance sheet shows position on a date.
Why can a company be profitable but run out of cash?
Accrual profit can rise while cash is tied up in receivables, inventory, or debt service.
What is the most important financial statement?
It depends on the question. Cash flow is critical for survival; income for performance; balance sheet for solvency and structure.
What is free cash flow?
A commonly used analytical measure derived from cash generation after required reinvestment; definitions vary, so check the formula used.
Do all companies use the same accounting rules?
No. Many U.S. public firms use U.S. GAAP; many non-U.S. firms use IFRS or local standards.
How often are financial statements published?
Public companies typically report quarterly and annually; private company cadence varies.
Where should beginners start?
Learn the structure of all three statements, then practice on a simple public company over two consecutive years.
Conclusion
Financial statements turn business activity into a disciplined story about profit, resources, obligations, and cash. The skill is not memorizing line items — it is connecting them. Read for trends, test profit against cash, and let the notes reveal what the headlines hide.
Quick Summary
Financial statements report performance (income statement), position (balance sheet), and cash movement (cash flow statement). Use them together, verify profit quality with cash flow, and read the notes before drawing strong conclusions.
Short Content Disclaimer
This article is educational and general in nature. It is not accounting, investment, tax, or legal advice. Standards and presentation details can change; consult qualified professionals and primary filings for decisions.
Authority sources:
Core definitions and statement linkages reflect standard financial accounting frameworks widely taught in professional finance education, including the conventional roles of the income statement, balance sheet, and cash flow statement under major reporting regimes.
Source: Corporatefinanceinstitute
Also Visit: financialblog
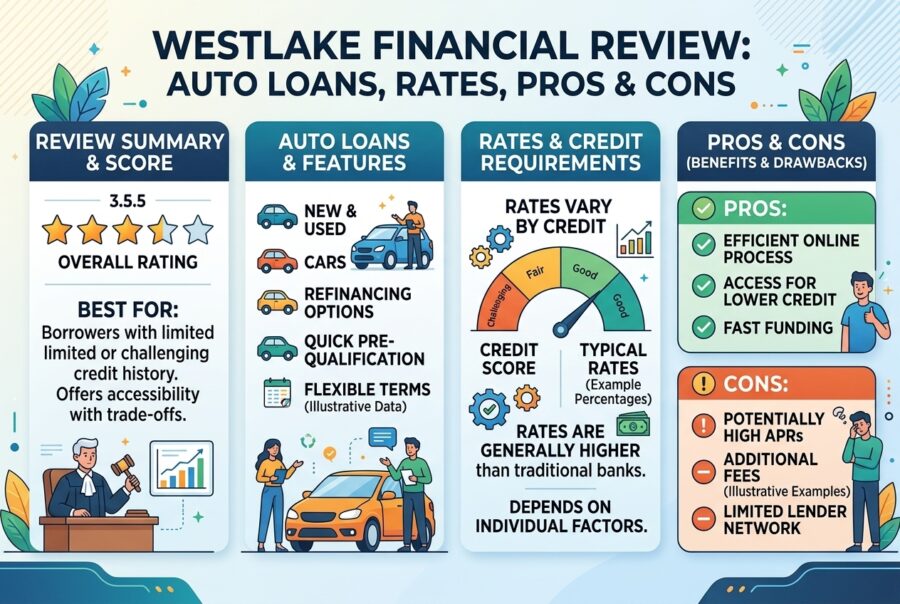
Westlake Financial is a major U.S. auto finance company that funds new and used vehicle loans primarily through partner dealerships, serving borrowers across a wide credit spectrum including subprime applicants.
It is an indirect lender: you typically get financing while buying a car at a participating dealer rather than taking a fully standalone online loan and shopping anywhere.
If a dealer mentions Westlake Financial during the F&I (finance and insurance) process, it usually means the store is trying to place your contract with a lender known for broader approval flexibility — often at a higher cost of credit than prime bank or credit-union financing.
Key Takeaways:
- Westlake Financial is a large dealer-network auto finance company
- Financing is typically arranged at partner dealerships
- Programs span prime to subprime credit profiles
- APRs and total costs can vary dramatically by tier and deal structure
- Negotiate vehicle price before financing details
- Compare any dealer offer against direct preapprovals when possible
- Long terms and add-ons often matter as much as the lender name
Background: What Westlake Financial Is?
Westlake Financial Services is a privately held automotive finance company headquartered in Southern California and associated with the Hankey Group’s auto-finance businesses. It specializes in acquiring and servicing automotive retail installment contracts from prime through subprime credit tiers and works with a very large network of new and used car dealerships across the United States.
Unlike a credit union that funds members directly, Westlake’s consumer-facing model is largely dealer-centered. That structure shapes almost everything about the borrower experience:
- Loan offers appear in the dealership finance office
- Vehicle, price, term, and add-ons are negotiated in the same transaction
- Approval programs are segmented by credit strength
- Servicing happens after the contract is booked
Company history materials describe a multi-decade expansion from local buy-here-pay-here roots into a national indirect auto lender with broad dealer coverage.
How Westlake Auto Financing Works?
Indirect lending in plain English
- You shop a vehicle at a partner dealership.
- The dealer submits your application to one or more lenders, which may include Westlake.
- Westlake returns an approval, conditions, and buy-rate parameters.
- The dealer presents a retail installment contract with an APR, term, payment, and optional products.
- If you sign, Westlake (or its servicing process) handles the account after funding.
This is convenient when you need a car quickly. It can also reduce transparency if you do not separate vehicle price from finance cost.
Commonly reported loan parameters
Consumer review sources frequently cite ranges such as:
- Loan amounts around $5,000–$30,000 (program-dependent)
- Terms often 48–72 months
- APRs that can span from the mid-single digits into the high 20s depending on credit and deal structure
- No single published minimum credit score for all programs
Treat every number as illustrative until you see a written contract. Dealer participation, state rules, vehicle age/mileage, LTV, and your profile all change the outcome.
Credit Tiers and Program Logic
Westlake and similar indirect lenders typically segment applicants into tiers (names vary by materials), such as stronger-credit programs and more flexible standard/subprime programs.
What that means for borrowers:
| Credit situation | What often happens | What to watch |
|---|---|---|
| Strong credit | More competitive APR potential, possible lower down payment | Still compare credit-union/bank preapprovals |
| Fair credit | Approval possible with tighter structure | Longer terms can inflate total interest |
| Poor credit / thin file | Higher chance of specialty finance placement | High APR + add-ons can create payment shock |
| Bankruptcy history | Some programs may still consider applications | Conditions and pricing can be strict |
| First-time buyer | Dealer may rely on flexible programs | Verify income documentation carefully |
Flexible approval is not the same as affordable credit. A “yes” with a 72-month term and expensive add-ons can cost far more than waiting, buying a cheaper car, or improving the down payment.
Rates, Fees, and the True Cost of the Deal
Auto-loan cost is a stack:
- Vehicle price (negotiate this first)
- Down payment / trade equity
- APR
- Term length
- Taxes and official fees
- Optional products (warranty, GAP, paint protection, etc.)
- Dealer reserve / markup between lender buy rate and contract rate, where permitted
Westlake’s role is financing. Many complaints in the broader subprime-dealer ecosystem come from the full package: high rate plus long term plus extras. Your defense is line-item scrutiny.
Practical cost checks before signing
- What is the APR?
- What is the finance charge in dollars?
- What is the total of payments?
- Which products are optional?
- Can the payment fall if I increase the down payment or shorten the term?
Pros and Cons of Westlake Financial
Pros
- Wide dealer network and broad credit consideration
- Potential path to approval when banks say no
- New and used vehicle financing through partners
- Ability to complete purchase and financing in one dealer visit
- Program variety across credit tiers
Cons
- Indirect model limits pure online, dealer-free shopping
- APRs for weaker credit can be very high
- Customer-service and fee complaints appear in public review ecosystems
- Loan size caps in some reported ranges may not fit higher-priced vehicles
- Easy to focus on monthly payment instead of total cost
Balanced verdict
Westlake can be a useful approval channel in the dealer network, especially for non-prime buyers. It is rarely the first place excellent-credit borrowers should stop if a credit union or bank preapproval is available.
Practical Tips: How to Use Westlake Financing Without Getting Trapped?
- Get outside preapprovals first from a bank or credit union when possible.
- Negotiate the car price as if paying cash.
- Only then discuss financing options, including Westlake if presented.
- Compare the dealer APR to your preapproval APR on the same term.
- Avoid stretching to 72 months unless the rate is competitive and the car will reliably outlast the loan.
- Decline add-ons by default, then add back only what you truly need.
- Confirm whether the vehicle meets lender age/mileage rules before falling in love with it.
- Read the retail installment contract for APR, payment, total of payments, and prepayment language.
- Keep copies of every page and the buyer’s order.
- If the payment only works with a long term and extras, the deal is too expensive — walk away.
Common Mistakes and Solutions
- Mistake: Shopping payment only
Solution: Compare total interest and total of payments. - Mistake: Signing under time pressure in the F&I office
Solution: Take the contract home or pause overnight on non-urgent purchases. - Mistake: Rolling negative equity into a new loan
Solution: Pay down the gap or choose a lower-priced vehicle. - Mistake: Ignoring LTV and down payment effects
Solution: A larger down payment can improve structure more than arguing over small rate differences. - Mistake: Assuming dealer-arranged financing is the only option
Solution: Outside lenders can still beat specialty APRs for many borrowers. - Mistake: Buying more car than income supports
Solution: Use a payment ceiling based on take-home pay, not dealer suggestions.
Future Trends in Dealer-Based Auto Finance
Expect continued pressure around:
- Longer loan terms and affordability stress
- Greater scrutiny of add-on products and fee practices
- Credit hardening or loosening with the broader economy
- More digital prequalification layered onto dealer networks
- Persistent demand for subprime capacity when vehicle prices stay elevated
Indirect lenders like Westlake sit at the center of that system because dealers need consistent funding sources for customers outside prime underwriting boxes.
Auto Financing Options Compared
| Option | Best for | Strength | Tradeoff |
|---|---|---|---|
| Westlake Financial (dealer-indirect) | Buyers needing flexible dealer financing | Broad credit reach via partners | Rate/fee risk; dealer-centric process |
| Credit union auto loan | Members with workable credit | Often lower APRs | Membership + underwriting standards |
| Bank direct auto loan | Existing banking customers | Relationship pricing potential | May decline weaker credit |
| Captive lender (OEM finance) | New-car incentives | Promotional rates on select models | Tied to brand/dealer systems |
| Online auto-loan marketplaces | Comparing multiple direct lenders | Transparent shopping | Still need vehicle that fits approval |
| Buy-here-pay-here lots | Very limited credit options | High approval likelihood | Very high cost; restricted inventory |
| Credit-card/cash mix | Small used-car purchases | Avoids installment interest | Impractical for most car prices |
| Personal loan for vehicle | Clear title strategies in some cases | Non-vehicle underwriting | Rates may not beat secured auto loans |
| Refinance lender later | Improving rate after on-time payments | Can reduce cost post-purchase | Not guaranteed; timing/LTV limits |
| Credit-builder delay | Non-urgent transportation needs | Better future APRs | Requires alternative transport short-term |
Who Should Consider Westlake — and Who Should Pause?
| Situation | Westlake fit | Better move first |
|---|---|---|
| Need a car soon, credit is fair/poor | Possible | Compare at least one non-dealer preapproval if available |
| Excellent credit, shopping new car | Weak primary fit | Bank/credit union/captive offers |
| Dealer says “this is the only approval” | Caution | Reprice vehicle, raise down payment, or leave |
| Payment only affordable at 72 months | Risky | Cheaper vehicle or more down payment |
| Wants fully online remote purchase financing | Weak fit | Direct lenders with broader dealer acceptance |
| Rebuilding after bankruptcy | Possible via flexible programs | Confirm conditions and total cost carefully |
| High-mileage older used car | Program limits may block | Verify vehicle eligibility early |
| Can wait 3–6 months | Often better to wait | Improve credit and savings |
Also Visit: OneMain Financial Review
FAQs
What is Westlake Financial?
An automotive finance company that funds vehicle installment contracts mainly through partner dealerships, across a wide credit range.
Is Westlake Financial a direct online car lender?
It is primarily an indirect, dealer-based financing source rather than a shop-anywhere direct bank replacement.
What credit score do you need?
Public materials and reviews often indicate flexible programs with no single universal minimum; pricing and conditions vary heavily by profile.
What APR should I expect?
Reported ranges are wide. Stronger credit can see much lower rates than subprime contracts, which can be expensive.
Can I refinance a Westlake auto loan later?
Refinancing may be possible through other lenders after on-time performance, subject to equity, credit, and rate markets.
Does Westlake finance used cars?
Yes, new and used financing is commonly described through dealer partners, subject to vehicle criteria.
Why do dealers use Westlake?
Dealers need lenders who can approve a broad mix of customers so sales are not lost when prime banks decline.
Are customer reviews mixed?
Yes. Convenience and approval access are positives; complaints about cost, fees, and servicing appear in public review channels, so read contracts carefully.
Conclusion
Westlake Financial plays a major role in U.S. dealer-arranged auto lending, especially where credit is imperfect and the sale depends on flexible funding. That can be the difference between leaving with a needed vehicle and being declined. It can also be the difference between a manageable loan and a high-cost contract dominated by term length and extras.
Your leverage is preparation: outside quotes, vehicle-price discipline, and total-cost math.
Quick Summary
Westlake Financial funds car loans through dealership partners and can approve a wide range of credit profiles. Use it as one financing path—not an automatic “yes.” Compare APRs, total payments, and add-ons, and bring outside preapprovals whenever you can.
Short Content Disclaimer
This article is general consumer information, not lending, credit, or legal advice. Auto loan rates, fees, program rules, and dealer practices change and vary by applicant, vehicle, and location. Verify all terms in your retail installment contract and consider independent financial guidance before signing.
Authority sources:
Background and product positioning draw on Westlake’s public company descriptions and widely published auto-loan review summaries of indirect dealer financing ranges and processes. Always confirm current terms with the dealer contract and official account servicing communications.
Source: westlakefinancial


Financial Advisor Guide: Types, Fees, Fiduciary Rules & How to Choose

Financial Statements Explained: Income, Balance Sheet & Cash Flow

Westlake Financial Review: Auto Loans, Rates, Pros & Cons
-
Finance9 years ago
These ’90s fashion trends are making a comeback in 2017
-
Finance9 years ago
The final 6 ‘Game of Thrones’ episodes might feel like a full season
-
Finance9 years ago
According to Dior Couture, this taboo fashion accessory is back
-
Finance9 years ago
The old and New Edition cast comes together to perform
-
Finance9 years ago
Phillies’ Aaron Altherr makes mind-boggling barehanded play
-
Finance9 years ago
Uber and Lyft are finally available in all of New York State
-
Finance9 years ago
Mod turns ‘Counter-Strike’ into a ‘Tekken’ clone with fighting chickens
-
Finance9 years ago
Disney’s live-action Aladdin finally finds its stars